Feature
12 of the Best Convertible Supercars on the Market
From great value for money, to the best tour cars and some special rarities, here are some of the best convertibles on the market right now.
September 22, 2026
Recently certain types of Modern Classics have seen values increase quite dramatically, has your insurance valuation changed to reflect that?
Modern classics, limited-production supercars and specialist performance cars can move in value surprisingly quickly. If your insurance valuation has not kept pace, the gap may only become obvious when you need the policy most.
Many enthusiasts buy these cars for emotional reasons, not financial ones. It might be the sound of the engine, the shape of the bodywork, the way it feels on the road, or simply because it is the car they always wanted. But over time, the car bought for passion can quietly become a valuable asset.
For owners of certain vehicles that fall into that criteria, it may be time to take another look at what is sitting in the garage.
Some cars remain simply enjoyable machines. Others become classics. A smaller number become genuinely collectible. What is striking today is that this is now happening to cars that, not long ago, were seen as modern performance cars rather than collector pieces.
The cars many enthusiasts grew up wanting are becoming the cars they are now buying. As demand increases and supply tightens, some values are rising quickly. The challenge is that values do not always move in a neat, predictable line.
A car that was worth one figure when you bought it can suddenly become considerably harder to find. A comparable example appears for sale at a much higher price. Another sells. Then another. Before long, the value you had in your head may no longer reflect the market.
There has been particularly strong interest around certain special-series Ferrari, Porsche, Lamborghini and McLaren models, while the wider collector-car market continues to show how much appetite exists for genuinely desirable, well-specified cars.
You do not have to trade cars regularly to spot the shift. Sometimes, it is enough to see what similar examples are now being advertised for. That raises an important question: when was the last time you checked what your car is actually insured for?
It is easy to renew an insurance policy without giving the valuation much thought. The renewal arrives, the car is still kept in the same garage, none of the details have changed, the direct debit still goes out and the paperwork gets filed away. Job done. Except perhaps it is not.
For starters, does your policy provide an agreed value, or would a claim be settled based on market value at the time of loss? This detail can make a substantial difference to the figure you would expect to receive should the worst happen to your pride and joy.
If your car has appreciated significantly since its agreed value was set, there could now be a meaningful gap between what you believe the car is worth and the amount it is insured for. That becomes especially important with modern classics and limited-production cars, because replacing one is rarely as simple as finding another used car.
The right colour
The right specification
The right mileage
The right service history
The right factory options
The right provenance
There might only be a handful of cars in the world that genuinely represent a like-for-like replacement. That is very different from replacing an ordinary used car.
Two cars that left the same factory can be worth very different amounts today. Colour, condition, mileage, service history, factory options and provenance can all influence value. Even one rare option can make a difference when there are only a few comparable cars available.
As more cars move into collector territory, these details become increasingly important. That is why a valuation from several years ago, or even several months ago in some cases, should not automatically be treated as a permanent figure. The market may have moved, and your car may have moved with it.
For cars whose values are changing, a pre-agreed value should not be treated as a set-and-forget figure. Reviewing it regularly helps ensure the insured value reflects the current market, not the market as it was several renewals ago.
If the worst happened tomorrow, would you be confident that your insurance reflects what it would actually cost to replace your car with the right example?
It is not about assuming your cover is wrong. It is about making sure it is still right.
This is where specialist advice can be valuable. A broker who understands performance, prestige and collector cars can help identify the details that may affect value, cover and replacement cost.
Title Partners, First Point Insurance, have worked with performance, prestige and specialist vehicles for nearly 30 years. Its approach goes beyond simply putting a value against a car, with specialist motor policies designed around the individual vehicle and the owner’s wider circumstances. That can include agreed value protection, choice of repairer and cover designed around the way these cars are actually used.
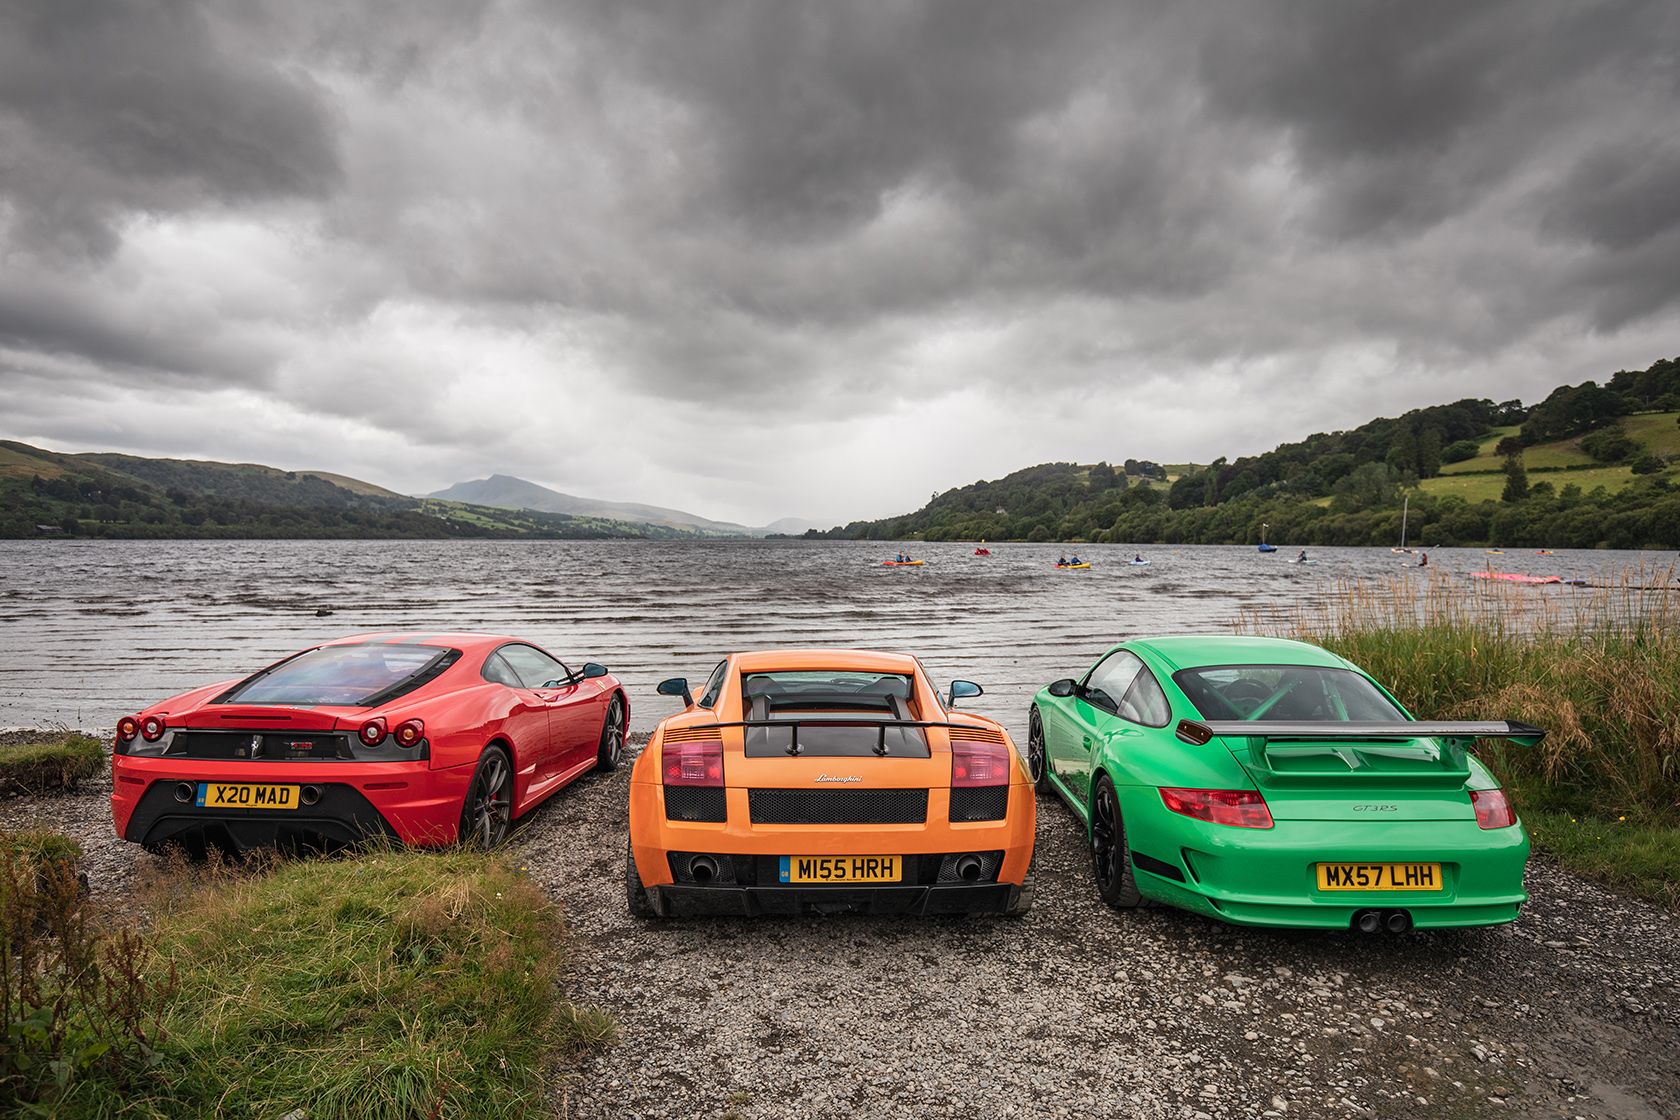
For many Supercar Driver members, the car is only one part of a much wider collection of valuable assets. There may be a home, watches, artwork, other vehicles, a business or a collection of cars that has grown quietly over the years. As those assets change in value, it makes sense to step back occasionally and look at the bigger picture.
You might already have it exactly right. Perhaps your Ferrari, Lamborghini, Porsche, McLaren or wider collection is insured for exactly what it would cost to replace today. But if you have not looked at the figure recently, it could be worth checking.
The funny thing about modern classics is that they do not always announce when they have become valuable. They sit in the garage during the week. You take them out on a Sunday morning. You drive them to a breakfast meet. You put them back under cover. Somewhere along the way, the car you bought because you loved it may have quietly become an appreciating asset.
If you are not completely confident that your agreed value still reflects today’s market, now is the time to check.
Speak to First Point Insurance for a confidential review of your specialist motor cover. The team can help you understand whether your current agreed value, policy structure and wider protection still match the car you own today — not the value it may have had several renewals ago.
To arrange a review, get in touch with First Point Insurance and ask for a specialist motor insurance appraisal. A short conversation now could help make sure your car, collection and wider assets are properly protected if you ever need to claim.